 The Institutional Platform × Sharemeister.ai
Stop selling a commodity.
Start building an asset.
Three disconnected systems are being sold as one company. None of them is consumer-facing, none of them compounds, and none of them survives its founders. Here is the platform that does — and what it actually costs to build.
Payroll firms own the rail. Employers own the paycheck. Carriers own the product. Nobody owns the employee — and the employee is the only thing in this business that appreciates.
So we give the rail away free, we give the employer the console free, and we take the one position no one else is contesting: a direct, trusted, portable relationship with the human being. That relationship is the asset. Her name is Bookah.
The diagnosis — three concepts wearing one coat
Audited 13 Jul 2026Every asset was retrieved and inspected: the pitch site, the payroll site, and the insurance brand. They do not add up to a company. They add up to three brochures and a book of business.
Payroll & benefits
A purchased jQuery theme — themekit, Bootstrap, Glide, Magnific, a Vimeo embed. The "Benefits Calculator" is a static form. No product, no account, no login. A brochure.
Health & insurance
Real carriers, real licenses, real producers — and a book of business that walks out the door with the founder. Distribution is a relationship, not a system.
The pitch platform
Seven static pages. No backend, no database, no API, no auth, no AI. "Emma" is a pre-written transcript typed into the HTML. The product URL is a parked domain.
The member database
60,000 potential members already in hand — first-party, already paid for, and doing nothing. No account, no relationship, no consumer surface to log into. The only thing here that appreciates, and it is sitting idle.
The deeper problem is not the engineering. It is that these three things sell a commodity. Cheap indemnity coverage is a price war with no floor. Carrier access is a relationship that retires. A benefits brochure is not a moat. There is no recurring product, no owned customer, no network effect and no transferable enterprise value — which is exactly why it cannot live beyond the people who built it.
And yet everything needed to build a real asset is already sitting here, unassembled: a licensed shelf, 4,500 payroll firms as distribution, a 60,000-record member database already paid for, and millions of employees who have never once been treated as the customer.
Start with the 60,000. They are the cheapest members this business will ever get — no acquisition cost, no cold list, no channel to negotiate. Connect them, and on day one there is a real book to watch, real windows to detect, and a readiness queue that is not a projection. Every other channel takes months to open. This one is already open, and it is being left closed.
Commodity → asset
The equity storyThe difference between what is being sold today and what an acquirer actually buys.
A commodity
- Priced against everyone. "Cheaper benefits" is a race to a floor you do not control — the carrier sets it.
- Rented distribution. Producers can leave. Payroll partners can switch. Nothing is locked in.
- No customer. The employee is a life to be enrolled, then never spoken to again.
- Founder-dependent. The carrier appointments, the relationships and the judgment live in one head.
- One-time revenue. Enroll, collect, move on. Nothing compounds.
- Unsellable. Diligence finds a book and a brochure. There is no platform to buy.
An asset
- Priced against nobody. Free to the payroll firm, free to the employer. There is nothing to undercut.
- Owned distribution. 4,500 payroll bureaus who cannot build a licensed shelf, plugged into one rail.
- A real customer. The employee has an account, a relationship, and Bookah — for life.
- Institutional. The judgment is encoded in the platform, the governance program and the audit log.
- Recurring and compounding. Every life event — marriage, a child, a job change, turning 65 — is the next transaction.
- Sellable. Recurring revenue, owned data, a network effect, and a product that runs without you.
The one sentence that changes the valuation: the policy is the employee's, not the employer's — so when she changes jobs, she keeps the coverage and she keeps Bookah. The relationship survives the payroll firm, the employer, and the founders. That is the difference between a book of business and a platform.
The market — three doors, one rail
Where the lives areThe distribution already exists. It is sitting inside payroll bureaus, PEOs, and a gig workforce nobody has ever offered benefits to. What is missing is a licensed shelf and a way to reach the worker directly.
Payroll bureaus
Four payroll authors alone reach 16.75M eligible employees — iSolved (5M), Asure (5M), PrismHR (4.25M), Execupay (2.5M). They own the rail and the employer relationship, and they have no licensed distribution to monetize it.
PEOs
Over 170,000 SMBs and an estimated 4–5M people. High-value, and the single most legally sensitive channel in the business — it runs on a separate track, gated until counsel clears it.
Gig · 1099 · self-employed
Roughly one-third of a ~150M non-farm workforce today, projected to pass two-thirds by 2028. They have no employer, so they have no payroll deduction and no open enrollment — and today, no benefits at all.
Every benefits platform in this category reaches workers through an employer. That works for channels 1 and 2. It cannot reach channel 3 at all — a gig worker has no employer to sponsor a plan, no deduction to run, and no enrollment window to sit inside.
A consumer-connected paycheck reaches them directly, and the same connectivity already covers 30+ gig platforms. The largest and fastest-growing channel in this market is the one the incumbent model cannot serve — and the one ours is built for.
How it earns — and who never pays
The corrected stackCarrier-funded, employee-side, on coverage the worker chooses and owns. Free to the payroll firm. Free to the employer. Every line below is built to survive diligence, which means some obvious-looking revenue is deliberately not here.
| Revenue line | Paid by | Basis | Status |
|---|---|---|---|
| Platform PEPM — enrollment + administration | Carrier | Per enrolled life, per month | Core |
| Supplemental & voluntary commission | Carrier | Commission on coverage the employee owns | Core |
| Card / ACH program | Carrier / program | Per life · own the rail, not a middleman | Stripe |
| Executive & individual life | Carrier commission | Individually issued, carrier-underwritten | Core |
| Technology & administration fee — payroll partners | Partner (optional) | Flat. Sale-independent. Never a % of premium, never scaled to enrollments. | Structural |
| Pre-tax §125 administration | — | Off by default. Post-tax deduction unless ERISA counsel and a CPA jointly clear it. | Off |
| Percentage overrides to unlicensed channel partners | — | Anyone earning sale-contingent compensation must be individually licensed and carrier-appointed. | Not offered |
Two lines are missing on purpose, and their absence is the product. Paying a channel partner a slice of premium, and running these products pre-tax through a cafeteria plan, are the two easiest dollars in this category — and they are the two that would put the whole model in front of a regulator. We do not price them in, so we never have to unwind them.
What the employer and the payroll firm pay
Why "$0 held by us" is a control, not a boast. Receiving premium and remitting it onward is money transmission, and it is licensed state by state. Premium collected by a licensed producer as agent of the insurer is not. The number stays zero by design.
What actually sets it apart
Ten, honestlyEvery platform in this category claims the same list. Here is the version where each claim is either structurally true or not made.
Zero cost to the employer
No premium, no PEPM, no admin fee, no per-employee charge. Full functionality. The business is never billed — and never sponsors, endorses, or contributes.
Coverage that pays alongside
Supplemental, wellness and voluntary plans that pay a set amount toward covered events. They work in addition to comprehensive health insurance — never instead of it, and we say so on every screen.
AI-guided enrollment, human-signed
Bookah educates, prepares and answers — anytime, in plain words, in English or Spanish. A licensed, appointed agent of record reviews and signs every enrollment. She never binds.
Multi-client management for SMBs
Fast setup, streamlined reconciliation, minimal administrative effort. One console across every employer, agent and payroll channel.
Carrier-funded economics
A per-employee-per-month fee from carriers pays for the platform — which is precisely why nobody else in the chain has to.
Group and individual payment
Employer-remitted deduction where the employer opts in. Consumer-connected split deposit where they don't — which is the only path that reaches gig, 1099 and self-employed workers at all.
Middleware, not another silo
Carrier integration, payroll integration, vendor data transfer, rules-based case setup. One canonical schema behind thin adapters — we own the abstraction, so no rail owns us.
Co-branded distribution
Aligned marketing to every channel partner, addressing what employers actually lose sleep over: security, retention, compliance, reporting, and cost.
Individual guaranteed issue
Carrier-issued, individually owned policies. No health questions on eligible products. The policy is the employee's — it goes with them when they leave.
Compliance as the product
Version-locked scripts, a replayable audit ledger, a licensed human on every bind, and a carrier-certification gate that blocks a product from shipping if it can't be certified.
One platform, three surfaces
Free where it must beNot three companies. One institutional platform for payroll, health and insurance, serving small-to-mid businesses and the payroll firms that reach them. The money comes from exactly one place — and it is not the people we are trying to recruit.
Payroll firms
4,500 payroll bureaus own the deduction rail and the employer relationship — and have no licensed distribution to monetize it. They plug in, co-branded, at zero cost and zero build. One canonical deduction schema; thin adapters per rail.
Employers
Census, enrollment, deductions, reconciliation, compliance — the admin that makes benefits feel like a second job, handled. The employer stays in control and pays nothing. Paid tiers only for genuine HR depth well beyond the free line.
Employees — Bookah
The consumer surface that does not exist today. Her own account, her own coverage, her own control — and a mama bear who is always there. She owns the policy. It goes with her when she leaves.
Where the money comes from
Carrier-funded, employee-side, on voluntary and supplemental coverage the employee chooses and owns — plus platform PEPM. Never the payroll firm. Never the employer. Free is not a discount we are absorbing; it is the acquisition strategy for the only customer that matters. We monetize the relationship, not the rail.
On the numbers already in the materials: four connected payroll authors reach 16.75M eligible employees, and the honest, legally-clear revenue stack runs $2.58M/yr on just 8,420 enrolled lives — not the $3.26M claimed, because three of the nine lines are blocked by a gate the same document raises. $2.58M that survives diligence beats $3.26M that does not.
Why free is not generosity — it is the compliance fix
The convergenceThe single best thing about this model is that the go-to-market strategy, the product design, and the legal defense are the same three decisions. Most platforms in this category have to choose. We do not.
Three problems. One answer.
The compliance work already done on this business identifies hard stops that could void the whole model. Every one of them is cured by the thing we wanted to do anyway.
And the same sentence that keeps us legal is the sentence that builds the asset: "Your employer doesn't sponsor, endorse, contribute to, or profit from this coverage — they only forward your payroll deduction. You own the policy. It goes with you when you leave." That is the ERISA safe harbor, the consumer promise, and the equity thesis — in one breath.
One gate comes before everything. Every product must be 100% insured by an authorized carrier, issued as a genuinely individual policy, with zero platform-retained risk and no association/trust/master-plan wrapper. We get that certified in writing by each carrier before a line of enrollment code ships. If a product fails, it does not ship. This is deliverable #1, not a launch-week scramble.
Bookah — the AI that makes it consumer-facing
Caring today. Protecting tomorrow.
"I've got your back."
The consumer face of the platform — built and demonstrable on request.
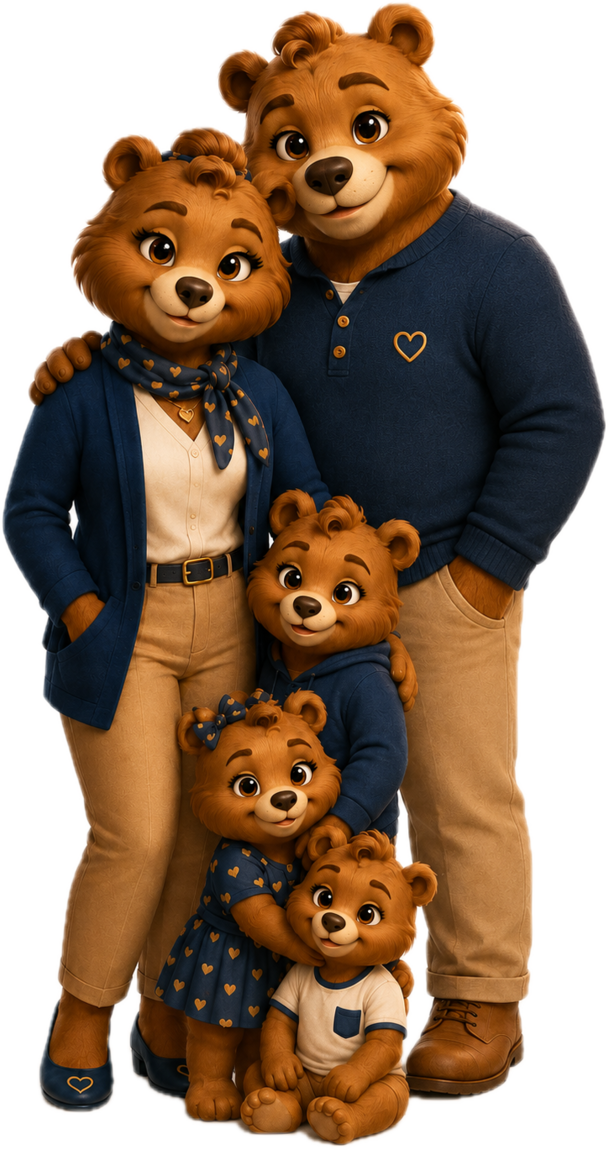
Not a chatbot bolted onto an enrollment form. Bookah is the consumer product — the reason an employee has a reason to come back, the reason the relationship outlives the job, and the reason this is an asset instead of a brochure. One governed AI, one audit log, one accountable owner. She wears a different tone at each surface; she never changes her guardrails.
"I've got your back."
Plain words, no jargon, no pressure. What fits her life, what it costs per paycheck, what happens next. She asks Bookah at 11pm and gets a real answer — then a licensed human confirms it.
Always there
She stays after the enrollment closes. New baby, new job, a hospital bill, turning 65 — every life event is a reason to come back, and the next transaction. Retention is the product.
The admin, handled
Census, enrollment status, deductions, reconciliation, compliance filings — answered and done, without an HR hire. The employer keeps control and spends no time.
The work, done
Bookah preps every enrollment, answers the questions, and hands a clean, signed-off file to the licensed agent of record. The payroll partner gets a benefits arm with no staff.
Her guardrails — non-negotiable, and they are also the sales copy
- She never binds. A licensed, appointed agent of record reviews and signs every enrollment.
- She always says what she is — an automated assistant, not a licensed agent — with one-tap escalation to a human.
- Carrier-approved, version-locked scripts. She never improvises coverage advice.
- She asks about real health insurance and never steers anyone away from it.
- "Alternative to major medical" is banned platform-wide, enforced at the output layer — not in a style guide.
- Every turn is logged and replayable. The audit trail is the examination defense.
- English and Spanish at parity, and genuinely accessible — keyboard and screen-reader paths throughout.
- Pre-tax is off by default. Post-tax deduction until counsel and a CPA jointly say otherwise.
What she costs to run. No paid model API is used during the build — content and scripts are authored directly. The meter only starts when a real person is in a real conversation. At scale that is roughly $1.50–2.50 per enrolled employee per year, billed at measured cost. That is the whole AI bill, and it is honest.
The six-month implementation plan
Aug 2026 → Jan 2027It opens with a diagnostic, because you cannot cost a build until you know what you are already paying for. Then a build sprint that produces a working platform, then four months rolling it onto real payroll partners and real employers. Something ships every month, and the riskiest thing goes first.
| Month | What ships | The proof |
|---|---|---|
| 1 · Aug Diagnostic + gate | The technology diagnostic. A full inventory of every system, vendor, contract, license and integration — what each costs, what it actually does, who owns it, and what breaks if it goes. Output: a stack ledger, a kill list, and an annualized savings number. The carrier gate, in parallel. Written certification per product (100% insured, individually issued, no trust wrapper, no retained risk). Canonical employee & deduction schema. Compliance ledger. | A signed certification per product — and a dollar figure for what we stop paying for |
| 2 · Sep Build sprint | Bookah goes live. Employee surface end-to-end: assessment → plain-language explanation → per-paycheck cost → licensed-agent sign-off. Payroll adapter #1. Employer console v1. | A real employee enrolls, start to finish, with a human signature on it |
| 3 · Oct | First payroll partner. Co-branded rail, employer onboarding, deduction sync and reconciliation running against live payroll. | Deductions reconcile automatically — no spreadsheet |
| 4 · Nov | Scale the rail. Payroll adapters #2–4 (iSolved, Asure, PrismHR, Execupay). Agent-of-record workspace. Bilingual EN/ES parity and the accessibility pass. | Four rails live · 16.75M eligible employees addressable |
| 5 · Dec | The asset shows up. Bookah's life-event engine — she stays after enrollment closes. Owner BI: enrolled lives, revenue per life, channel P&L. Gig / 1099 pilot opens on the consumer-connected rail — the channel the employer model cannot reach. | Returning members · a channel no competitor can serve |
| 6 · Jan | Handover. Your team on the platform, runbooks, the governance program in your name, steady-state operations. | It runs without us — and without the founders |
The diagnostic — what it inventories, and what it kills
This runs first because every later number depends on it. You cannot price a platform, negotiate a carrier, or size a rev-share until you know the true cost and the true dependency map of what is running today. It is also the cheapest month of the engagement and usually the one that pays for the other five.
What we inventory
- Every system and vendor — what it costs annually, what it does, who owns the contract
- Renewal dates and exit clauses — so we never get trapped paying for something we've replaced
- Overlapping tooling — the same job being paid for twice in different departments
- Rev-share takers vs real infrastructure — who is a partner and who is a toll booth
- Every integration — files, feeds, SFTP, APIs, and what silently breaks if a vendor leaves
- The PHI/PII surface — where regulated data actually moves, and whether a BAA exists for each hop
- Credentials and keys — who holds them, where they rest, what is shared
- Licenses and seats — paid for, provisioned, and not used
Where the savings come from
- Middlemen on rails you should own. Card and ACH processing routed through a reseller is margin leaking on every transaction.
- Thin revenue lines that cost more than they return. Each one carries an integration, a contract, and a data-processing agreement. Some are net negative once you count the compliance surface.
- Duplicate ben-admin and enrollment tooling. Consolidating onto one canonical schema retires the rest.
- Legacy platforms kept alive for one feature. Absorb the feature, retire the platform.
- Unused seats and auto-renewing licenses. Unglamorous, immediate, and almost always there.
- Vendors that are the compliance risk. The most expensive line item is the one that stops the business — killing it is a saving you cannot put on a spreadsheet.
What it does not do. It does not cut anything load-bearing to make a number look good. Payroll rails and carriers are irreplaceable and stay. The diagnostic separates what you must rent from what you are renting because nobody ever asked — and it hands you the second list with a price on it.
The commercials
Priced to your termsFour lines. A two-month build paid upfront, a retainer pegged to the cost of two employees, a single-digit revenue share, and third-party costs paid directly by you at cost — never marked up, never through us.
The sprint that produces the platform: the carrier gate, the canonical deduction layer, the compliance ledger, and Bookah in production with a licensed agent signing behind her. This is the heavy, senior work that de-risks everything after it — so it is paid for as a build, not amortized into a retainer.
Pegged to the fully-loaded cost of two average employees — roughly $75,000 each per year ($62k salary plus ~21% payroll tax and benefits), so $150,000/yr, so $12,500 a month. You are hiring a team you do not have to recruit, onboard, insure or keep.
Two kinds of upside, because we are paid to build an asset you intend to sell, not just run a service. The 8% revenue share (single digits, as you asked) is ongoing — it does not step down. It is what being in business together looks like: we keep a stake in what the platform earns for as long as it earns. A founding equity stake is the ownership side of the same thing — a piece of the company we are building, so we also share the exit we help create.
AI and infrastructure run on your accounts, under your keys, on your invoice. We provision and operate them; we never resell them. You see exactly what the platform costs to run, and you keep it if we ever part ways. We'll run the diagnostic and work to reduce reliance on third-party SaaS costs that can be consolidated into the primary platform.
The figures below are estimates, not quotes — actual spend depends on volume, usage, and each vendor's pricing at the time.
| Total cash to Sharemeister | Amount | When |
|---|---|---|
| Upfront build — 2 months | $37,500 | 50% kickoff · 50% first live enrollment |
| Implementation retainer — 6 × $12,500 | $75,000 | Monthly |
| Revenue share — 8%, ongoing | Only if it produces | A standing partnership · paid out of revenue, not capital |
| Founding equity stake — 5–10% | Ownership | We share the exit we help build |
| AI & third-party services (estimated) | $0 to us | Direct to your accounts, at cost · metered, not quoted |
| Total fixed cost, full engagement | $112,500 | Everything else is performance-based or at cost |
What that buys. A working institutional platform — payroll, health and insurance for small-to-mid businesses and the payroll firms that reach them — with a consumer surface that does not exist anywhere in the business today. For roughly the cost of two employees for six months, plus a build fee, plus a share that only pays if the thing works.
Honest ledger. Revenue figures are drawn from the existing materials and marked down where a legal gate blocks the line; they are hypotheses until discovery confirms the record count, the contactable and consented share, the lines of business and the payroll pipeline. Our costs are not hypotheses. The build fee and the retainer are fixed — no escalation, no overage. AI and third-party spend is metered on your own accounts at what it actually costs, so there is no number here we could quietly inflate. We do not estimate vaguely: every line is priced, metered, or performance-based.
The Institutional Platform — payroll, health & insurance · featuring Bookah, the consumer assistant · Built by sharemeister.ai